₹20,000 Down Payment on a Bike: What Could the EMI Look Like in India?
Overview
Planning to buy a motorcycle with just ₹20,000 upfront in India? This guide works out the EMI on the Hero Splendor Plus, which costs about ₹87,000 on-road in Delhi, and compares it with the Honda Shine 125 and Bajaj Pulsar 125. It covers loan tenures, interest rates and the running costs that sit beside the instalment. It is written for first-time buyers and commuters watching every rupee.
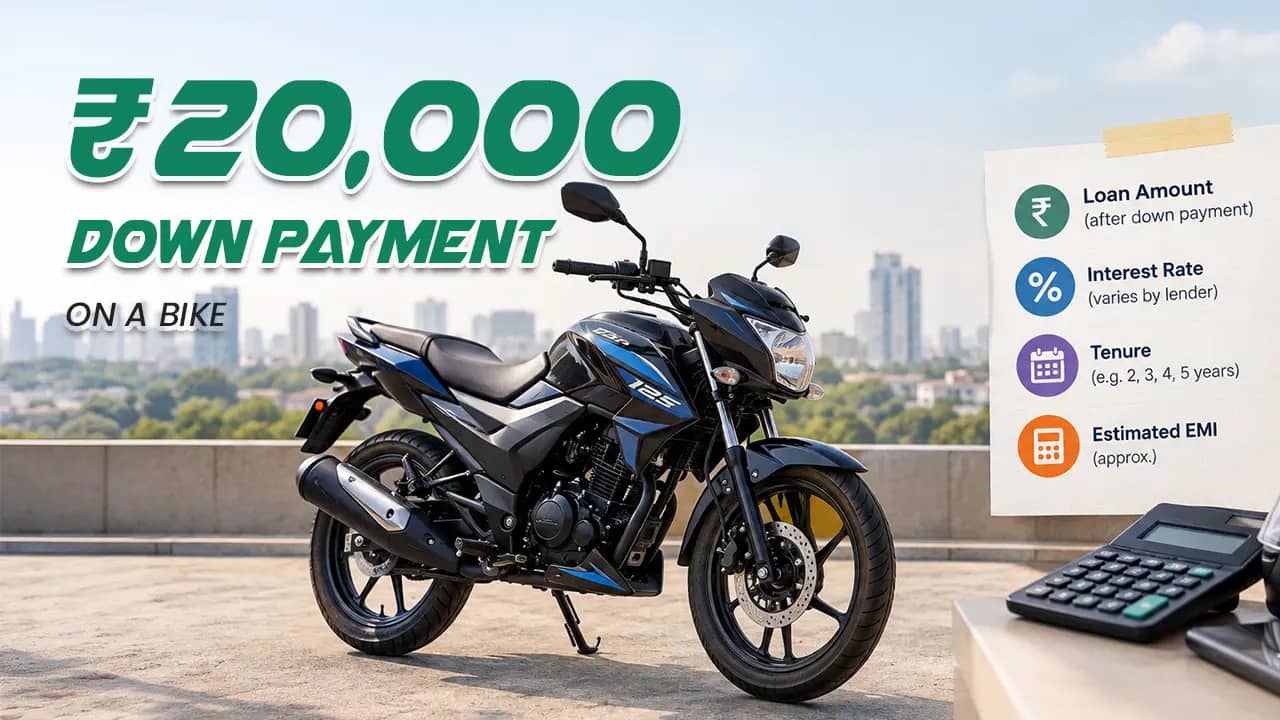
A ₹20,000 down payment on a bike is enough to bring home a Hero Splendor Plus in India, with an EMI of roughly ₹2,190 a month over 36 months. That works on an expected ex-showroom price of around ₹74,000 and a Delhi on-road price near ₹87,000. With festive-season dealer offers running, the number is worth pinning down before you walk into a showroom. Here is how it moves with tenure, interest rate and the bike you choose. The Splendor Plus runs a 97.2cc air-cooled engine making about 8 PS and 8.05 Nm. Nothing thrilling on paper. But it sells in huge numbers because it returns 60-plus kmpl in city traffic and rarely asks for anything in return. The ex-showroom price is only the start. Insurance (expected near ₹7,500), road tax, registration and handling charges push the Delhi on-road figure to about ₹87,000. Subtract your ₹20,000 and you are borrowing roughly ₹67,000. In Mumbai, where on-road prices run higher at around ₹92,000, the loan grows to about ₹72,000 and the 36-month EMI to roughly ₹2,360. One trap catches first-time buyers. Some lenders finance only the ex-showroom price. In that case insurance and registration come out of your pocket on top of the ₹20,000. Ask the dealer’s finance desk which basis they use before you sign anything. These figures assume a ₹67,000 loan at 11% interest, a rate that good-credit borrowers can expect from banks and larger NBFCs. They are estimates, so treat the lender’s quote as final. Stretching from 36 to 48 months trims the instalment by about ₹460 but costs you another ₹4,200 in interest. For a bike that will be worth far less in four years, that is a poor trade unless cash flow is genuinely tight. Thirty-six months is the sensible middle. Interest rate matters less than people fear at this loan size. At 18%, the same 36-month loan costs about ₹2,420 a month, only ₹230 more than at 11%. Tenure and down payment move the needle faster. Every extra ₹5,000 you put down cuts the 36-month EMI by about ₹165. Yes, but it gets tighter. The Bajaj Pulsar 125, which Drivio has covered, carries a 124.4cc engine with 11.8 PS and 10.8 Nm. At an expected ex-showroom price near ₹85,000 and a Delhi on-road price around ₹1,00,000, you would borrow about ₹80,000. The 36-month EMI at 11% comes to roughly ₹2,620. The Honda Shine 125 sits in between. Its 123.94cc motor makes 10.59 PS and 11 Nm, and the expected ex-showroom price is around ₹78,000. It is the smoother commuter of the two, while the Pulsar is the one that feels quicker off the line and better on a flyover. Going the other way, a ₹20,000 down payment on a bike like the Honda Shine 100 (about ₹63,000 ex-showroom, expected) shrinks the loan to roughly ₹55,000 and the EMI to about ₹1,800. If your priority is the lowest possible monthly outgo, that is the number to beat. An EMI is never your real monthly bill. Take 1,000 km a month, a normal figure for an office commute in Gurugram or Pune. The Splendor Plus at about 60 kmpl burns roughly 16.7 litres, which at ₹103 a litre is ₹1,720. Add the ₹2,190 EMI and you are at about ₹3,900 a month. The Pulsar 125, at around 50 kmpl, uses 20 litres, or about ₹2,060 in petrol. Add the ₹2,620 EMI and the monthly total climbs to roughly ₹4,680. That is nearly ₹800 more than the Splendor, every month, for the same ₹20,000 upfront. Servicing widens the gap. Expect roughly ₹3,500 to ₹4,500 across the first 10,000 km on the Splendor, covering oil changes, chain lubrication and brake adjustments. The Pulsar will likely run ₹5,000 to ₹6,000 over the same distance. A simple rule: if your total monthly outgo crosses about 15% of take-home pay, the bike starts to pinch. For the Splendor, that means a salary above roughly ₹26,000. A CIBIL score above 750 is the single biggest lever on your interest rate. Below 650, expect quotes at the higher end of the 14% to 18% band, and some dealers will quietly steer you to costlier NBFC schemes. Check the processing fee, which commonly runs ₹500 to ₹2,000, and ask for a waiver during festive offers. Read the foreclosure clause too, since some lenders charge 2% to 5% for early closure. “Zero down payment” deals look attractive but usually hide a higher rate or a longer lock-in. For most Indian commuters, the Hero Splendor Plus on a 36-month loan is the right answer to a ₹20,000 budget. It keeps the combined EMI and fuel bill under ₹4,000 and holds resale value better than most rivals. Buyers who ride 40 km or more each way, or who want better highway manners, should look at the Shine 125 or Pulsar 125. They should take a 48-month term only if the monthly total stays under that 15% line. And if your credit score is shaky, saving another ₹10,000 before you buy will save you more than any dealer discount. Check the on-road price and EMI for the Hero Splendor Plus in your city on Drivio.What a ₹20,000 Down Payment on a Bike Really Gets You
EMI at 24, 36 and 48 Months
Is a ₹20,000 Down Payment Enough for a 125cc Bike?
The Running Cost Your EMI Doesn’t Show
Getting the Loan on Better Terms
The Verdict
Pick the Splendor Plus on a 36-month loan: about ₹2,190 EMI plus ₹1,720 in monthly fuel keeps the total near ₹3,900. Daily commuters with take-home pay above ₹26,000 can handle that comfortably. Riders who want more punch should stretch to a Pulsar 125 or Shine 125, but only with a 48-month term and a clean credit score. Anyone with a weaker score should save a bigger down payment first.