Bike EMI on ₹1 Lakh: Down Payment, Monthly Cost and the Real Running Bill
Overview
Bike EMI on ₹1 lakh comes to roughly ₹1,739 a month in India with ₹20,000 down and a 60-month loan at 11% interest. This guide breaks down EMIs for 36, 48 and 60-month tenures, shows how down payment and tenure change total interest, and compares the TVS Raider 125, Honda SP 125, Bajaj Pulsar 125 and Hero Splendor Plus. It also covers real monthly fuel costs at ₹103 a litre, service and insurance expenses, and why dealers' flat-rate offers cost more than they sound.
Bike EMI on ₹1 lakh works out to roughly ₹1,740 a month in India if you pay ₹20,000 down and spread the balance over 60 months at 11% interest. Dealers rarely say that number out loud, and they say the total repayment even less. With Diwali about a month away and showrooms pushing finance schemes, do the sums before the salesman does them for you.
Bike EMI on ₹1 Lakh: What 20% Down Really Costs
"₹1 lakh" means two different things in a showroom, so settle that first. As an on-road budget, it buys a mid-range TVS Raider 125, which lands near ₹99,000 on-road in Delhi, or an SP 125 or Pulsar 125 with room to spare. As an ex-showroom price, it is a bigger commitment. RTO and insurance push the bill towards ₹1.12 lakh, and Mumbai adds roughly ₹3,500 on top. The numbers below assume ₹1 lakh on-road.
Twenty per cent down is ₹20,000, which leaves an ₹80,000 loan. At 11% over 60 months, the EMI is ₹1,739. You repay ₹1,04,364 in all, so the loan costs about ₹24,400 in interest, and the "₹1 lakh" bike has quietly become a ₹1.24 lakh purchase by the last instalment. Tenure changes that picture fast.
Going from 36 to 60 months cuts the monthly outgo by about ₹880 but adds over ₹10,000 in interest. The 48-month loan is the sensible middle. It costs ₹330 a month more than the 60-month plan and saves roughly ₹5,100. Stretch the down payment to ₹25,000 and that same 48-month loan drops to about ₹1,940 a month.
Down payment moves the number as much as tenure does. Pay 10% and the 60-month EMI rises to about ₹1,957. Pay 30% and it falls to about ₹1,522. The "zero down payment" offers on dealer banners fund the full ₹1 lakh, which means an EMI near ₹2,174 and about ₹30,500 in interest, usually at a higher rate than the one you would get with money on the table.
Best Bike Under ₹1 Lakh: Raider 125, SP 125 or Splendor Plus?
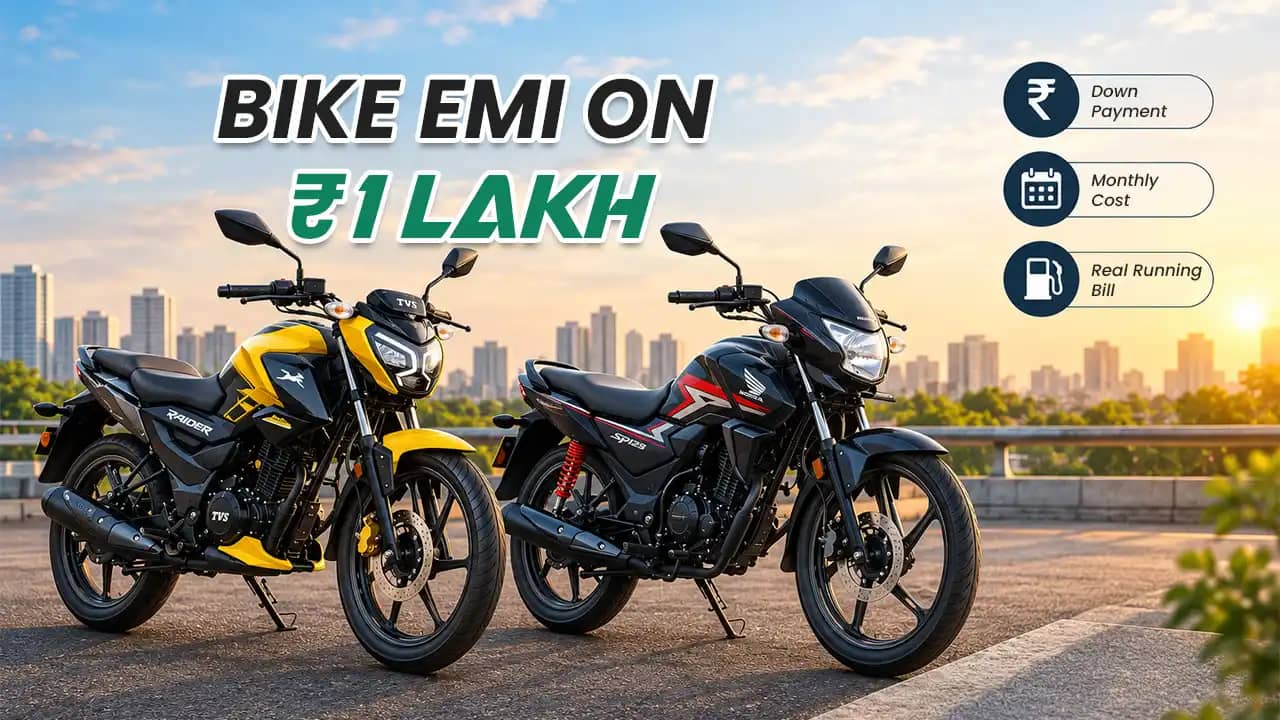
The TVS Raider 125 is the pick if you want a 125 that feels like one. Its 124.8cc engine makes 11.38 PS and 11.2 Nm, and the base drum variant costs about ₹83,000 ex-showroom in Delhi, likely near ₹92,000 on-road. Honda's SP 125 (123.94cc, 10.7 PS, 10.9 Nm) starts around ₹86,000 ex-showroom. It gives up a little power for Honda's refinement and resale. The Bajaj Pulsar 125 (124.4cc, about 11.6 PS, 10.8 Nm) starts near ₹84,000 and is the loudest, most aggressive of the three.
Then there is Hero's Splendor Plus, which Drivio has already covered in detail. At 97.2cc and about 8 PS, it is the cheap, sensible choice, with an ex-showroom price of roughly ₹74,000–75,000 and an on-road figure likely near ₹86,000. A 20% down payment and a 60-month loan on that works out to about ₹1,500 a month. It leaves ₹14,000 of your budget unspent, and in Delhi's stop-start traffic that gap is hard to argue with.
The Monthly Bill Beyond the EMI
Fuel at ₹103 a litre
Petrol is the second EMI nobody budgets for. A Raider returning a real-world 55 kmpl (TVS claims 56.7 on the ARAI cycle) burns about 18 litres over 1,000 km, which is ₹1,870 a month. The Splendor Plus, at around 65 kmpl, needs 15.4 litres, or ₹1,590. Add the EMI and the Raider costs about ₹3,600 a month to run against about ₹3,100 for the Splendor. That ₹500 gap buys roughly 40% more power, which matters on a highway but not much at a red light.
Service and insurance
At 10,000 km a year, plan on three or four paid services at likely ₹600–900 each with oil, so ₹2,500–3,500 over the year. The first insurance renewal after 12 months likely lands between ₹1,500 and ₹2,000 for a 125cc bike. Put it together and year one costs roughly ₹46,000 in EMI, fuel and servicing, on top of the ₹20,000 you paid upfront.
Where the Loan Quote Gets Expensive
A dealer's "7% flat" sounds cheaper than the 11% reducing rate used above. It is not. Flat rates charge interest on the full ₹80,000 for all five years, so 7% flat means ₹28,000 in interest and an EMI of ₹1,800. That is roughly 12.5% on a reducing balance. Ask every lender for the reducing-balance rate, the processing fee and the foreclosure charge in writing. One percentage point of interest on this loan is worth about ₹2,400 over 60 months, so a ten-minute comparison between two lenders pays better than any free helmet.
The verdict is simple. If you ride 30 km or more a day and want a bike that will not feel slow in two years, take the mid-range Raider 125 on a 48-month loan with ₹25,000 down. If your commute is short and every rupee counts, the Splendor Plus gives you a ₹1,500 EMI and a lower fuel bill. Before any dealer quotes you a number, check the on-road price and EMI for the TVS Raider 125 in your city on Drivio.
Taking a ₹1 lakh on-road bike on loan with 20% down means an ₹80,000 loan and a ₹1,739 EMI over 60 months, costing about ₹1.24 lakh in total. The 48-month plan saves roughly ₹5,100 in interest for ₹330 more a month. Running costs add around ₹1,870 in monthly fuel for a Raider. Our verdict: riders covering 30 km daily should pick the TVS Raider 125; budget-focused buyers are better served by the Splendor Plus, with an EMI near ₹1,500 a month.