TVS Jupiter Price Down Payment and EMI for Daily Household Travel
Overview
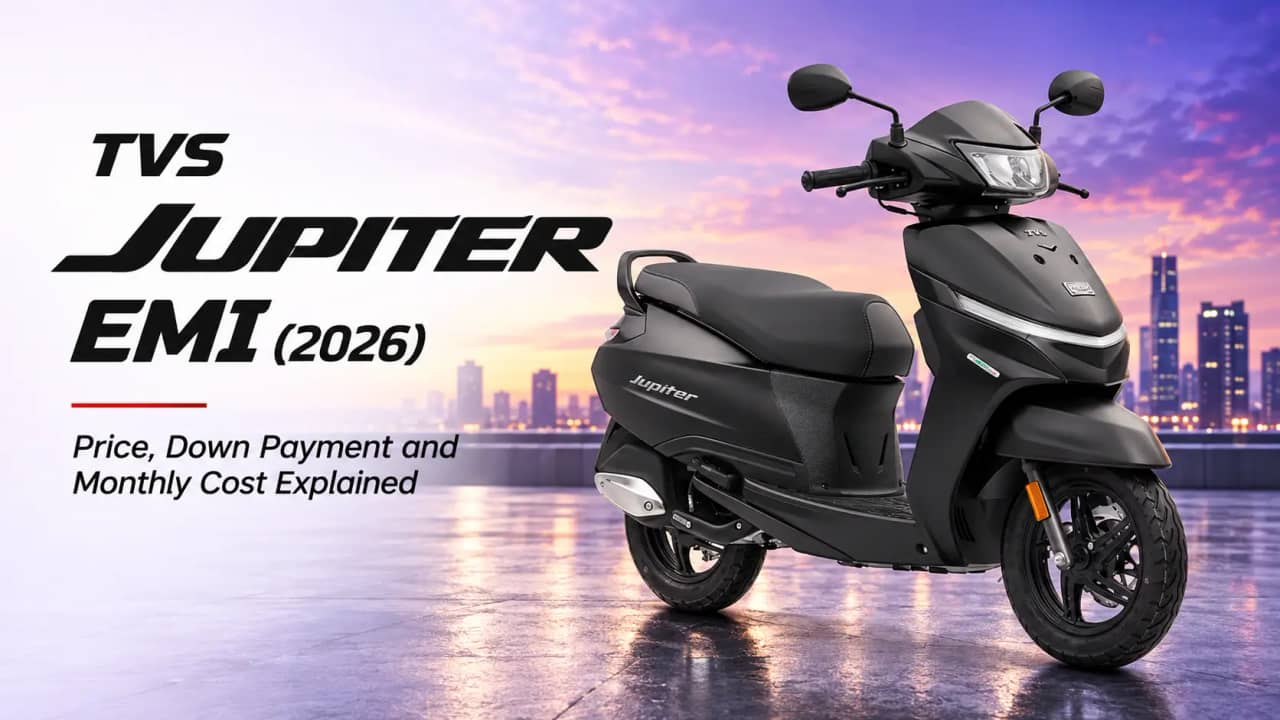
Budgeting for the TVS Jupiter starts with its published ₹74,125 price reference and a current city-specific on-road quotation. Using an assumed ₹90,000 invoice, 20% down payment and 11% illustrative interest, the 36-month EMI is about ₹2,357. The guide compares financing choices and recurring costs, including low-mileage household affordability. Local registration, insurance and exact equipment can change the amount you need.
The TVS Jupiter’s listed starting price is ₹74,125 ex-showroom in the current 2026 research. For the calculations, this guide assumes a ₹90,000 on-road bill; that is a transparent budget, not a verified registration-and-insurance quotation. Finance divides the balance after your deposit into instalments with interest. The useful starting point is whether the entry or a higher trim meets your household’s needs, because the badge alone does not fix the price.
Research checked 14 September 2026. Published references: model pricing and information; TVS manufacturer catalogue. Prices and availability can change before delivery.
TVS Jupiter Price in India
The current listing gives a ₹74,125–₹89,825 ex-showroom range across six versions. The broad spread means a top Jupiter can sit near other 125cc scooter quotations. The official Disc SmartXonnect configuration is one named higher trim; its features should not be applied automatically to the entry bike. Exact current prices for every intermediate version were not reconciled here. Request a dated variant sheet and assess braking equipment, display and colour premiums separately.
Ex-showroom is the vehicle’s advertised price before the complete ride-away bill. Obtain separate amounts for registration and road tax, insurance, and any other applicable invoiced charges. Identify optional accessories and service packages individually. Do not add tax again where it is already included in the quoted vehicle price. No exact RTO fee or insurance premium is assumed here: the finance model starts from a hypothetical complete invoice, which must be replaced with your dated quotation.
TVS Jupiter On Road Price Across Cities
As a location-specific reference, BikeDekho’s current Delhi listing gives an indicative on-road range of ₹86,011–₹1,03,266. This is a published estimate, not a dealer-verified offer; check variant, insurance and the quote date. The separate EMI budget below is an assumed invoice, not this listing’s calculated total.
A Delhi household should not use a Noida or Gurgaon registration figure simply because those cities are nearby. In Agra, Varanasi or Prayagraj, compare local workshop access with any out-of-town saving. A Mumbai buyer who needs a scooter for short station journeys may travel fewer kilometres than a Patna office commuter; their running budgets should differ even if the vehicle is identical. Check annual usage before accepting fuel-savings claims as a reason to finance more.
Use the same comparison method beyond the main metros. In Uttar Pradesh, this includes Lucknow, Noida, Ghaziabad, Kanpur, Agra, Varanasi and Prayagraj. Haryana buyers in Gurgaon/Gurugram, Faridabad, Panipat, Karnal and Hisar need the correct registration jurisdiction. Compare Mumbai, Pune, Nagpur, Nashik and Thane quotations on equal insurance terms. In Bihar, include Patna, Gaya and Muzaffarpur; in Gujarat, Ahmedabad, Surat, Vadodara and Rajkot; in Madhya Pradesh, Bhopal, Indore, Gwalior and Jabalpur. Different variants or optional packages can explain a price gap even within one state. Published estimates, where cited, still need dealer confirmation; the assumed invoice is not presented as a local dealer price.
For a petrol vehicle, compare the same manufacturing specification and insurance cover before judging a state-to-state price gap. A cheaper quote with fewer accessories may simply be a different package. Check each charge instead of applying an invented uniform on-road markup.
TVS Jupiter EMI: How Much Will You Pay Every Month?
All figures below are illustrative, using an assumed ₹90,000 on-road invoice and 11% nominal annual reducing-balance interest. This is not a guaranteed Drivio rate or a lender offer. Actual pricing depends on credit history, income, borrower profile, vehicle and lender eligibility. The 12–60 month choices show the mathematics; a lender may not offer every term or deposit combination, particularly for a used vehicle.
Loan amount = On-road price − Down payment. EMI = P × r × (1 + r)^N ÷ [(1 + r)^N − 1], where P is the financed principal, r is the annual rate divided by 1,200 and N is the number of monthly instalments. The calculation assumes monthly payments in arrears and no financed fees. Rupee values are rounded; the final lender schedule may adjust the last payment.
For example, a ₹90,000 purchase with ₹18,000 upfront leaves ₹72,000 to finance. At the assumed 11% for 36 months, the EMI is approximately ₹2,357. Total instalments are about ₹84,859, including ₹12,859 interest. Adding the deposit gives a purchase-and-interest outlay of roughly ₹1,02,859, before any fees outside the assumed invoice and ongoing ownership expenses.
TVS Jupiter Finance Options
For a household scooter, the best deposit is one that reduces repayment without consuming funds needed for essential bills. Avoid relying on a small EMI alone: a long term can keep a modest purchase on the budget for years. Ask whether the processing fee is added to the financed amount or collected upfront. If family income varies, test the instalment against a lean month rather than the strongest month in the past year.
Ask a bank, NBFC or dealer-arranged provider for a written personalised quotation. Typical application checks may include identity and address evidence, PAN where required, bank statements, salary evidence or business-income records, and the vehicle quotation. Requirements and minimum income vary; no universal eligibility threshold is assumed. Compare the annual percentage rate or equivalent all-in cost, processing charges, repayment schedule and total amount payable. Clarify fixed versus floating rates, late-payment charges and the prepayment terms applicable to that agreement.
A flat interest rate is not directly comparable with a reducing-balance rate carrying the same percentage. Ask for the cash flows and total repayment before choosing. If a fee is added to the principal, it also attracts interest under the agreement; if collected upfront, it raises the cash required at delivery. Either way, it should appear in the comparison.
Exploring financing through Drivio
Buyers can check the latest on-road price and explore available financing options for the TVS Jupiter through Drivio. Ask for a quote identifying the city and variant. Approval, rate, amount financed and eligibility remain subject to the lender and customer profile; no approval or lowest-rate guarantee is made here.
TVS Jupiter Down Payment
At the assumed invoice, a 10% deposit is ₹9,000 and a 40% deposit is ₹36,000. Increasing upfront cash by ₹27,000 reduces the 36-month EMI from about ₹2,652 to ₹1,768, a monthly reduction of ₹884. The 20% and 30% alternatives in the table provide intermediate choices. These percentages model the whole on-road bill; an actual lender may fund only selected invoice components, so the delivery-day cash requirement can be higher.
With 20% down, 24 months costs approximately ₹3,356 monthly and ₹8,538 total interest. Extending to 60 months reduces EMI to ₹1,565 but raises interest to ₹21,927. The longer term therefore adds about ₹13,389 interest. Choose the term using the monthly surplus left after essential spending; a lower instalment does not mean a cheaper purchase.
TVS Jupiter Running Cost
The 48km/l used below is a planning assumption. Short cold-start journeys, traffic and frequent stops can change the result. Low monthly use does not remove time-based servicing and insurance obligations. Divide a real annual insurance renewal quote by twelve to create a reserve; do not treat that reserve as a published Jupiter service cost. Also account for punctures and tyre ageing when the scooter is used infrequently.
Illustrative petrol calculation: 650km ÷ 48km/l × an assumed ₹100/litre = about ₹1,354 monthly. If economy is 20% lower at 38.4km/l, the same travel costs ₹1,693. Petrol at ₹100 is a model input, not a verified city pump price. At the original assumption, finance plus fuel totals approximately ₹3,711 monthly. Insurance renewal, service, tyres, repairs, parking and protective equipment are additional; obtain actual quotes for those items.
Specifications and ownership implications
The current Jupiter is a 113.3cc scooter. TVS’s Disc SmartXonnect page specifies CVT transmission, 5.9kW and up to 9.8Nm with assist, plus 33-litre under-seat storage. This should not be confused with specifications for older Jupiter generations.
Check the manufacturer specification for the exact year and variant: TVS Jupiter information. Untested fuel economy, battery life and service prices are not supplied as facts.
TVS Jupiter vs Other Scooters
The Honda Activa is an appropriate everyday scooter alternative, while the Jupiter 125 and Suzuki Access 125 help test whether a move to 125cc provides enough benefit. Compare storage with your own belongings, manoeuvring in a tight parking space and comfort at low speed. A more expensive scooter is not automatically unsuitable, but its premium should buy something useful. Normalize the cash price before comparing monthly repayments.
To translate any genuine quotation difference into finance, consider an illustrative ₹7,000 higher on-road bill. Keeping 20% down and the same 11% rate over 36 months adds ₹1,400 upfront and about ₹183 monthly. This is a comparison method, not an asserted price gap to a named competitor. Recalculate with the actual competing quotes and their own running costs.
Used TVS Jupiter Financing
A used Jupiter can refer to a previous engine generation, so do not borrow this new model’s specifications for an older registration. Verify year, variant, odometer consistency and service invoices. Look for damaged plastics hiding structural repair and check the CVT’s behaviour from rest. A low used price can be reasonable, but the finance must be assessed alongside likely catch-up maintenance, transfer expenses and the condition of consumables.
For a hypothetical used transaction, suppose the agreed price is ₹54,000, lender valuation ₹49,000, and the advance 75% of that valuation. Finance would be ₹36,750, leaving ₹17,250 cash before transfer costs and fees. At an illustrative 14% over 24 months, EMI is ₹1,764. These are invented transaction inputs for calculation, not observed resale prices or an available offer. Confirm outstanding hypothecation and the applicable ownership-transfer process before payment.
Who Should Consider the TVS Jupiter?
The Jupiter makes sense for practical local travel when the rider is comfortable with its size and controls. Someone prioritising stronger load-carrying performance should test the 125 as well; someone with dependable charging and substantial mileage should compare an EV using a complete cost model. For limited household use, keeping the purchase simple and the repayment manageable may matter more than a long list of connected features.
Is Financing the TVS Jupiter a Good Option?
Use your own transport allowance rather than a universal salary rule. For illustration, an allowance of ₹5,500 minus the modelled ₹2,357 EMI and ₹1,354 petrol leaves about ₹1,789 monthly for insurance reserves, service, tyres, parking and contingencies. This is a budgeting example, not an income eligibility threshold. If your actual bills exceed the remainder, adjust the deposit, variant, term or purchase timing. Existing debt and essential household spending come first in that calculation.
The Jupiter’s listed ₹74,125 starting price can rise with trim and local on-road costs. Financing an assumed ₹90,000 purchase after 20% down payment gives about ₹2,357 EMI at 11% for 36 months. Low usage still requires insurance and time-based maintenance, so do not judge affordability from petrol alone. Choose equipment that serves the household, and check current prices plus financing options through Drivio before accepting the lender’s personalised repayment agreement.